Money can be a touchy subject, especially regarding our closest relationships. Whether we like it or not, finance plays an integral role in our partnerships, families, and friendships. So, how can we foster healthy attitudes and productive conversations around this sensitive topic?
In this blog, we want to explore money’s psychological impact on our bonds with others. We’ll unravel why finances stir up so many emotions in our connections, examine communication breakdowns and breakthroughs, and equip you with actionable tips to enhance financial harmony in your relationships.
And what better time to dig into the psychology of relationships and money than the month of Valentine’s Day and love? In February, many couples may exchange gifts, splurge on dates or romantic trips, and bask in the joy of romance. But we should also evaluate our financial partnership: Did we maintain open communication and alignment on priorities throughout the year? Could we establish new habits or spending boundaries that foster closeness and stability? We hope this blog empowers you and your loved ones with the tools to build a greater financial understanding beyond this season of candy hearts.
Our goal is to help you reflect on your money mindset when relating to loved ones so that you can pinpoint growth areas and make positive shifts. Because our financial behaviors, values, fears, and anxieties don’t develop in a vacuum, relationship dynamics profoundly influence them. Let’s discover how and why regarding the psychology of love and money!
According to a 2021 survey by the Harris Poll on behalf of the American Institute of Certified Public Accountants (AICPA), 73% of married or cohabiting Americans say they experience relationship tension due to financial decisions. We all think differently about money, but getting on the same page with your partner is critical to avoiding long-term and sometimes irreconcilable problems.1
The Psychology of Money
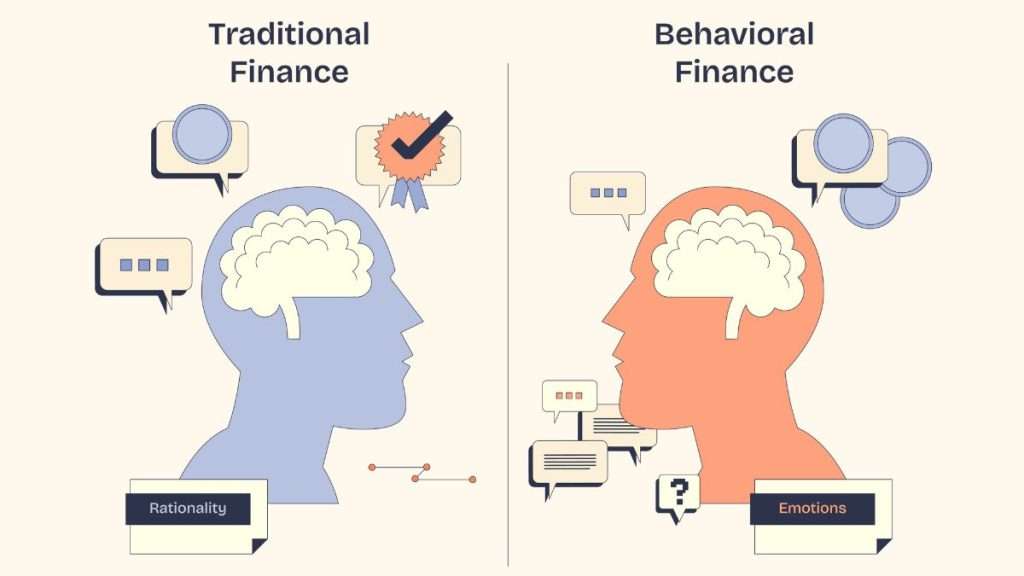
A psychological dimension of how we think and feel about money impacts our behavior; some see money as a source of pride, comfort, or security, while others feel a sense of guilt, stress, or shame around their finances. With these different perspectives and values, financial conflicts are often inevitable in our closest relationships.
Several theories seek to explain the psychological impact money has on partnerships and families:
- Learning theory implies that we adopt our attitudes and beliefs about money from our parents or social environments during our upbringing. If we observe dysfunctional behaviors, they subconsciously shape our habits.2
- The evolutionary psychology perspective associates money with survival and security, which can lead to feelings of anxiety and stress when money is scarce. Financial hardship can quickly erode relationships by triggering our instinctual fight-or-flight response.3
- Social or economic exchange theory suggests that people use money as a form of reward or punishment in relationships, creating power imbalances and feelings of insecurity or inferiority.2
We all have preconceived notions and biases about money that we bring to our marriages and other relationships. Figuring out what causes stress can go a long way toward happiness.
Five Points of Financial Friction
While some of your feelings about money may be hardwired into your psyche, getting more in sync with your significant other is possible if you know where the friction points are. Here are five financial issues that have the potential to derail even the best match.3
- Differences in Financial Goals
Couples often have different financial goals. One partner may want to buy a vacation property, while the other dreams of extensive travel. Figuring out what timeline makes sense and agreeing on a strategy may help you work better as a team and develop a shared vision of your financial future.
By consulting with a financial professional, you can collectively articulate what you want to pursue in the short and long term and map out a well-constructed strategy. - Limited Communication About Big Money Decisions
When one partner makes all the major financial decisions without input, it can make the other partner feel diminished. Agreeing on financial guardrails that trigger a discussion before purchases over a certain dollar amount can help both parties feel heard.
We encourage all client meetings to include both members of the relationship so that each person is aware of and agrees with the financial strategy and any changes. This practice is designed to build strong, trusting client connections. - Financial “Infidelity”
Financial “infidelity” is concealing or being untruthful about money. It includes betrayals of trust, such as hiding accounts or credit cards from your partner. It’s also surprisingly common. A 2022 poll from the National Endowment for Financial Education study found that 39% of respondents say they’ve hidden cash, statements, bills, or purchases from a partner, and 21% say they’ve lied about finances, debt, or money earned. When asked why they commit financial infidelity, 38% say they believe some aspects of money should be private, 34% fear disapproval from a spouse, and 33% say they’re embarrassed or fearful of finances and don’t want to share.3
As difficult as you may find it, being transparent about your financial moves and creating a supportive environment where you and your partner feel comfortable sharing good and bad financial information can help. - Different Spending Habits
If you and your partner have different spending habits, you know they can lead to fundamental disagreements. Although you may never be able to change each other’s mindsets about spending, there could be ways to come to a happy medium.
A financial professional can give you an outside opinion on your spending behaviors and hopefully guide you to reach mutually agreeable common ground. - Income Differences
In some relationships, one partner may earn more than another, which can cause tension. Money imbalances are not only about who makes more; they can also include differences in spending habits and financial goals. Honesty is the foundation of a healthy partnership. Being transparent can prevent partners from feeling either inadequate or resented.
Financial professionals can play a role as you pursue financial harmony.
Relationships are seldom effortless. You need to put the time in and work on it every day. When it comes to the stresses that finances add to the mix, financial professionals can help navigate conflicts.
We assist couples in managing their financial differences by:
- Identifying financial goals and priorities, assisting couples in clarifying their individual and shared financial objectives, focusing on alignment, and managing potential conflicts.
- Developing a comprehensive financial strategy to create a personalized financial roadmap that addresses investment decisions and retirement considerations.
- Educating couples on financial concepts and strategies to help them make informed decisions when managing their finances.
- Providing guidance that offers insights based on the couples’ financial circumstances and risk tolerance.
While celebrating Valentine’s Day this month, we must acknowledge that a lack of communication, differing values, and power imbalances can often turn natural psychological inclinations about money and occasional financial challenges into real personal strains. Open communication and teamwork can be key to a healthy relationship. As financial professionals, we can strengthen the financial side of your relationship by creating roadmaps that help ease friction.
- BusinessWire.com, February 4, 2023
https://www.businesswire.com/news/home/20210204005261/en/Relationship-Intimacy-Being-Crushed-by-Financial-Tension-AICPA-Survey - PsychologyToday.com, December 7, 2022
https://www.psychologytoday.com/us/blog/how-make-better-choices/202212/the-psychological-impact-money-relationships - Experian.com, February 17, 2023
https://www.experian.com/blogs/ask-experian/money-issues-that-can-hurt-relationship/#:~:text=A%20massive%2073%25%20of%20married,impacts%20intimacy%20with%20their%20partner